

The Bank of Albania has officially published the new regulation “On Interchange Fees for Card-Based Payment Transactions”.
The new regulation transposes the European Union directive of the same name from 2015, and its main purpose is to reduce the fees that banks charge merchants for accepting card payments.
Starting from 1 January 2027, payment service providers may not apply an interchange fee higher than 0.2% of the transaction value when the transaction is made with a debit card and 0.3% of the transaction value when it is made with a credit card.
For the purposes of the regulation, an interchange fee is a fee paid for each transaction directly or indirectly between the issuer and the acquirer involved in a card-based payment transaction. Net compensation or any other agreed remuneration shall be considered part of the interchange fee.
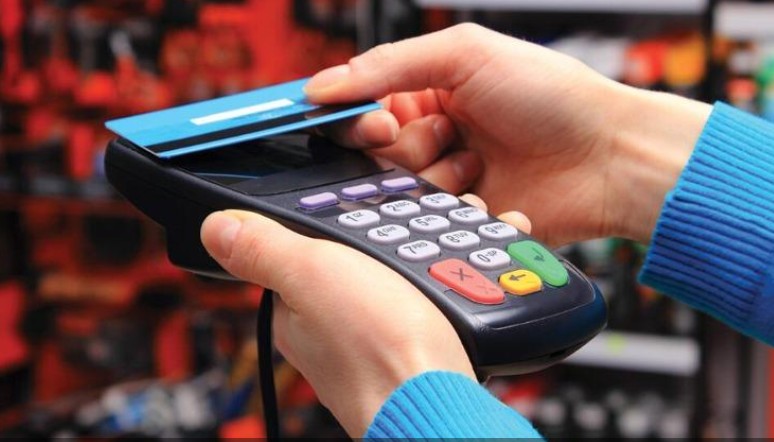
In simpler terms, the interchange fee is the fee paid by the merchant’s bank that accepts the payment to the bank that issued the buyer’s card, whenever the consumer makes a payment using a card.
Setting limits on this cost element is expected to bring a significant reduction in the total commission that merchants pay for card sales.
According to sources from the banking sector, the current level of interchange fees can be estimated on average at around the 1.5% threshold, but this is referred to as an indicative level, because the rate of commissions varies depending on the type of business activity.
However, interchange fees are not the only element of the total commissions that a merchant pays for each card sale. This structure also contains two other elements.
Scheme or network fees are fees charged directly by global card payment scheme companies, such as Visa or Mastercard.
Both banks (the issuing bank and the acquiring bank) pay these fees because they use the global scheme network to authorize and process the transaction. They are small per-transaction fees, but they accumulate in large volumes.

In addition, the commission also includes the fee called the acquirer markup.
This is the part retained by the merchant’s bank (the one that has installed the POS device or the online payment gateway). This fee covers the cost of the device, technical processing and the risk the bank takes on by working with the merchant.
Adding up all the commission items together, today the commission a merchant pays to the bank for card payments can reach more than 3% in the case of payments with cards issued abroad. For payments with cards issued by domestic institutions, commissions are lower.
Setting a cap on one of the commission items (interchange fees) is expected to significantly reduce the total commission.
According to the Bank of Albania, the level of commissions could fall to 1%, but representatives of the banking sector do not believe the reduction can be at these levels, and see the 1.5% threshold as a more realistic level.
For transparency regarding the breakdown of the types of fees charged to the payment beneficiary (merchant), the regulation requires that, after the execution of an individual card-based payment transaction, the payment service provider of the payee must provide the payee with the reference enabling the payee to identify the card payment transaction; the amount of the payment transaction in the currency in which the payee’s payment account is credited; the amount of any fee for the card payment transaction, separately indicating the merchant service fee and the amount of the interchange fee.
However, this article of the regulation will enter into force only on 1 January 2028, due to the time needed by banks and card payment schemes to detail the data./ Monitor